
ICICI Home Loan Interest Rate: What It Is Today
What is the ICICI home loan interest rate today?
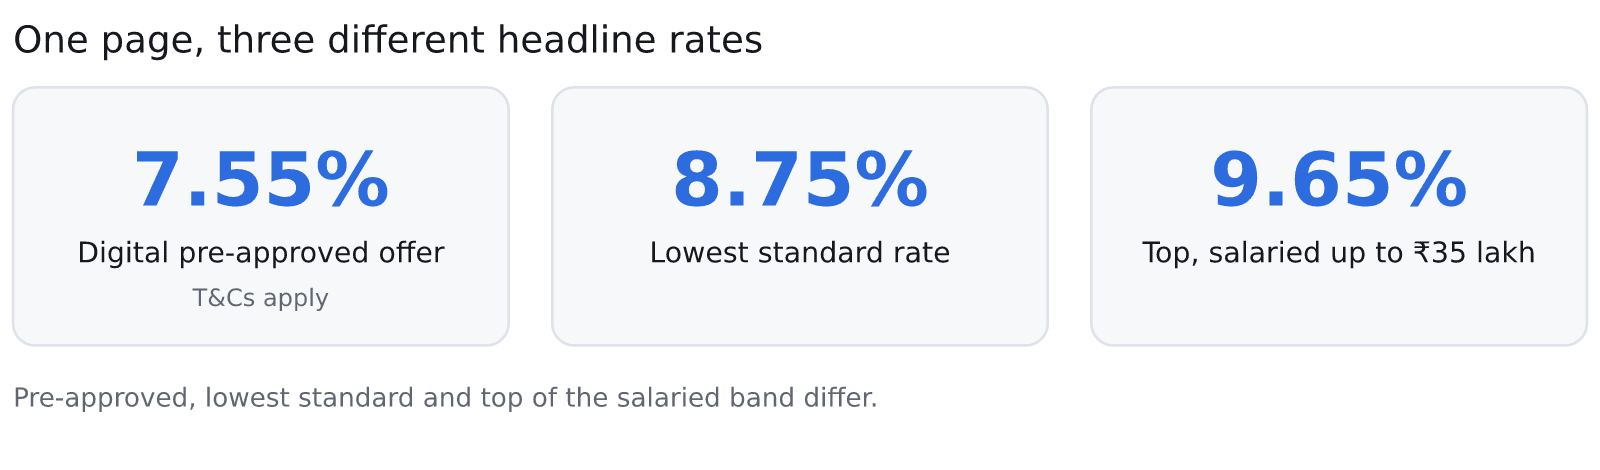
In short: The ICICI home loan interest rate on the bank's page (18 October 2026) runs 8.75% to 9.65% for salaried borrowers up to ₹35 lakh, valid till 31 October 2026. Your own rate depends on your profile.
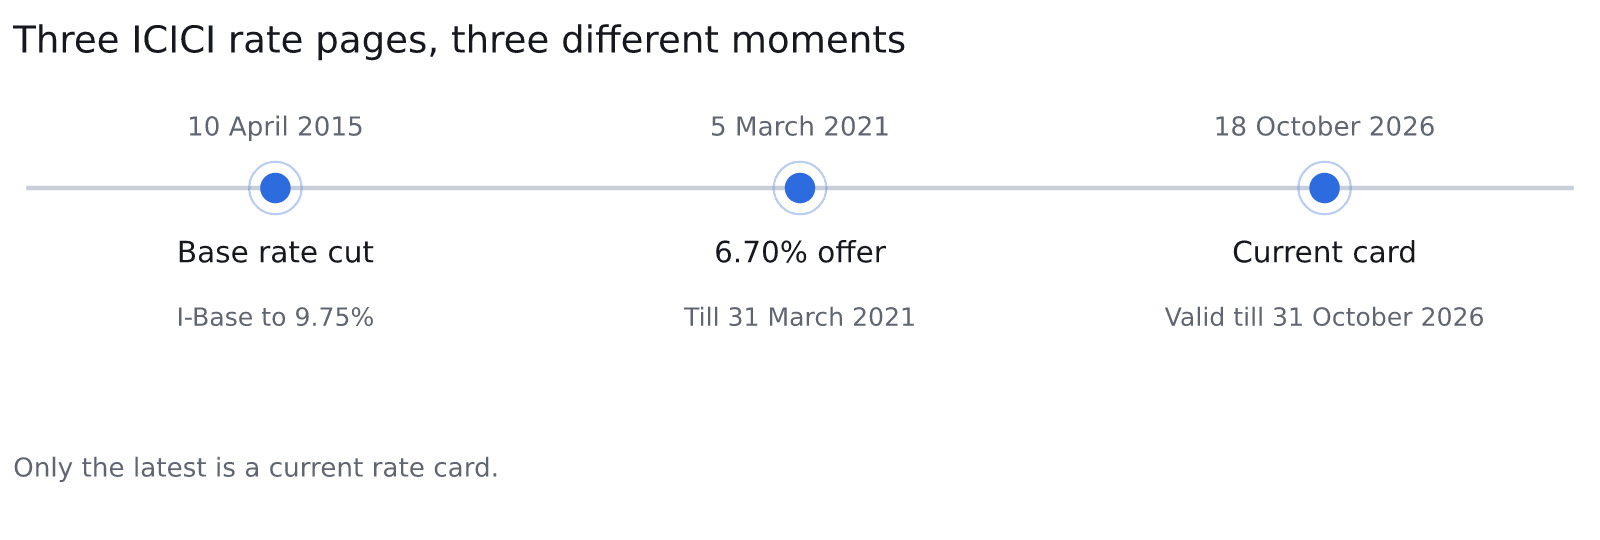
You've probably seen "ICICI home loan at 6.70%" in the search results. That was a March 2021 offer that ended on 31 March 2021. It still ranks because the news page never went away, and it's the first number most people see. It's not the rate you'd get.
If you want to test a rate against your own loan, enter your outstanding loan, EMI and rate on Butter Money's overpayment page to see what a lower rate would save you. Below: the current card, how a rate is built, the fees, and what to check before you apply.
The current ICICI rate card
I read ICICI's home loan interest rates page on 18 October 2026. It says the special, standard and fixed rates are valid till 31 October 2026. After that date the figures below may change, so check the date on the page before you rely on any of them.
ICICI's floating rates by loan size, as listed on 18 October 2026
| Loan size | Salaried | Self-employed |
|---|---|---|
| Up to ₹35 lakh | 8.75% to 9.65% | 8.75% to 9.80% |
| ₹35 lakh to ₹75 lakh | 8.75% to 9.80% | 8.75% to 9.95% |
| Above ₹75 lakh | 8.75% to 9.90% | 8.75% to 10.05% |
Source: ICICI Bank home loan interest rates
Three more lines on the same page matter.
- Digital pre-approved offer: 7.55% p.a. The page says T&Cs apply, that it depends on bureau score, and that it is only for pre-approved loans taken through the digital journey. Check whether you'd be offered it.
- Special rates by score: 8.75% for a score of 800 and above. For 750 to 800 it's 8.75% for salaried and 8.85% for self-employed.
- Fixed rates: the page lists terms of 24, 37, 60 and 120 months and a full term. The 120-month fixed rate is 10.75% to 10.85%, well above the floating range.
Notice how wide the bands are. The top sits close to a point or more above the bottom. That gap is where your profile does its work, and it's ICICI's call, not a calculator's.
Why do old ICICI rate headlines still rank?
Because they were press releases, and press releases don't expire. Look at what two of them actually said.
In April 2015, ICICI cut home loan rates by 25 basis points. Its base rate fell to 9.75% from 10 April 2015. In March 2021, it cut the rate to 6.70% from 5 March 2021, for loans up to ₹75 lakh. The release itself says "These revised rates will be available till March 31, 2021." It adds that rates depend on bureau score, profile and customer segment.
So a 2021 headline shows how low rates went for a few weeks. A 2015 one belongs to a different system altogether. Neither tells you what to expect today.
How is your ICICI home loan rate built?
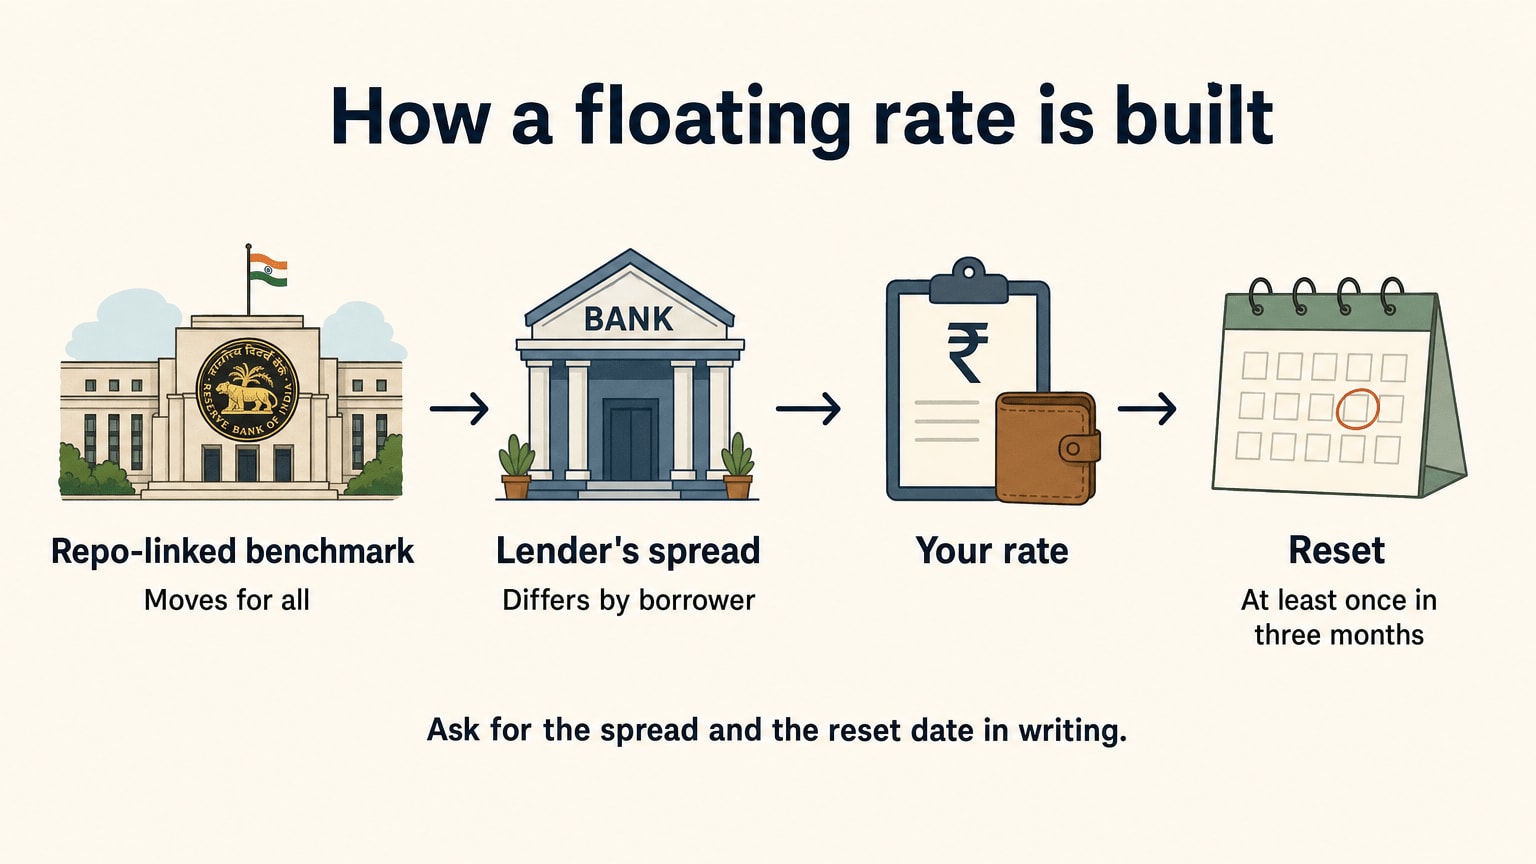
A floating rate is a benchmark plus a spread. The benchmark moves for everyone. The spread is the lender's own, and it's the part that differs between borrowers.
ICICI's page says its rates are linked to the repo rate, and shows "Repo rate effective 08 October 2026" at 5.50%. The RBI's own press release says the Monetary Policy Committee raised the policy repo rate by 25 basis points to 5.50 per cent on 7 October 2026. The two dates differ by a day, and I couldn't find out why. The figure agrees.
What I couldn't find on the page is ICICI's spread over the repo rate. It isn't printed. So ask for it in writing.
Why does the benchmark reset? RBI circular RBI/2019-20/53, dated 4 September 2019, requires new floating rate loans from 1 October 2019 to be linked to an external benchmark. It also says the rate under the external benchmark shall be reset at least once in three months. Your sanction letter gives your reset date. Butter Money's repo rate post explains how a change reaches your EMI or tenure.
What does the gap cost you in EMI?
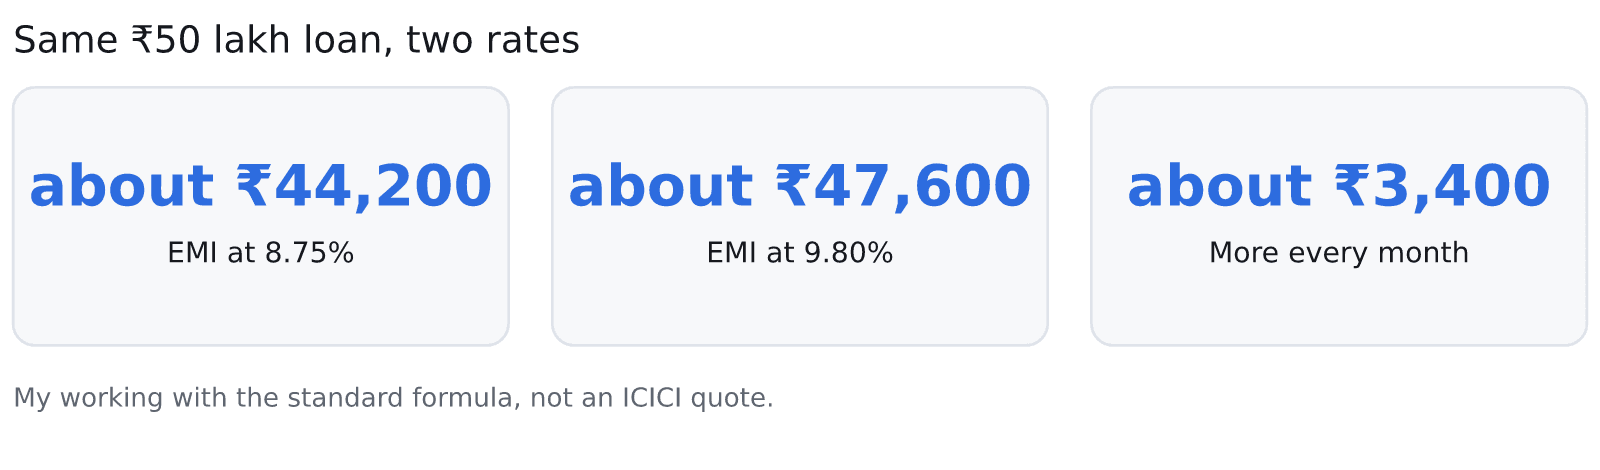
Take a loan of ₹50 lakh over 20 years. That falls in the ₹35 lakh to ₹75 lakh slab, where the salaried range is 8.75% to 9.80%, so I used both ends. This is my own working with the standard EMI formula, not an ICICI quote.
At 8.75%, the EMI comes to about ₹44,200. At 9.80%, about ₹47,600. That's about ₹3,400 more every month, for 240 months. Same loan, same flat. Only the rate changed.
That's why a rate card is a starting point. Your number sits somewhere in that band, and the sanction letter tells you where.
What else does ICICI charge?
The rate page lists a processing fee of 0.5% of the loan amount plus applicable taxes. For prepayment it says "foreclosure or prepayment-related charges, if applicable" and sends you to ICICI's Home Loan Service Charges page. I haven't read that page, so I won't give you a figure. Ask ICICI whether your loan, floating or fixed, carries one.
Valuation, legal and stamp duty come on top, and none of them is in the rate. The valuation and the final amount belong to ICICI.
What should you check before you apply?
- Read the rate page and note its validity date. Today that is 31 October 2026.
- Know your score. The card ties its lowest rates to scores of 750 and above. The free CIBIL score check post shows how to pull your report. If it's lower than you hoped, see how to improve your credit score.
- Run three rates in your EMI. The lowest on the card, the highest, and one in between. Choose the EMI you could pay in a bad month.
- Ask for the spread, the benchmark and the reset date in writing.
- Compare. ICICI is one lender. See how HDFC and SBI publish theirs, then put the rate, fees and tenure side by side.
Approval, rate and timeline are ICICI's decision. Nobody else can promise them.
Frequently asked questions
What is the ICICI home loan interest rate?
ICICI's page, read on 18 October 2026, lists standard floating rates of 8.75% to 9.65% for salaried borrowers up to ₹35 lakh, valid till 31 October 2026. A 7.55% digital pre-approved offer also appears, with T&Cs. Your rate depends on your profile.
Is the ICICI home loan rate 6.70%?
Not now. ICICI's 6.70% rate took effect on 5 March 2021 and, per its release, was available till 31 March 2021. It still appears in search because the news release is still online.
Is the ICICI home loan rate fixed or floating?
Both exist. The page lists floating rates, and fixed rates for 24, 37, 60 and 120 months plus a full term. The 120-month fixed rate is 10.75% to 10.85%.
Does a higher CIBIL score get a lower ICICI rate?
The page lists special rates by score and says the pre-approved rate depends on bureau score. ICICI's 2021 release says rates depend on score, profile and segment. How much your score moves your rate is ICICI's decision.
What is the ICICI home loan processing fee?
The page lists 0.5% of the loan amount plus applicable taxes. Confirm the current amount with ICICI.
Does the repo rate change my ICICI EMI?
The page says rates are linked to the repo rate, which the RBI set at 5.50 per cent on 7 October 2026. Under RBI circular RBI/2019-20/53, the benchmark rate is reset at least once in three months. Your sanction letter shows your reset date.


